
Court Rules Head Office Expenses Cannot Be Taxed Without Proper Valuation
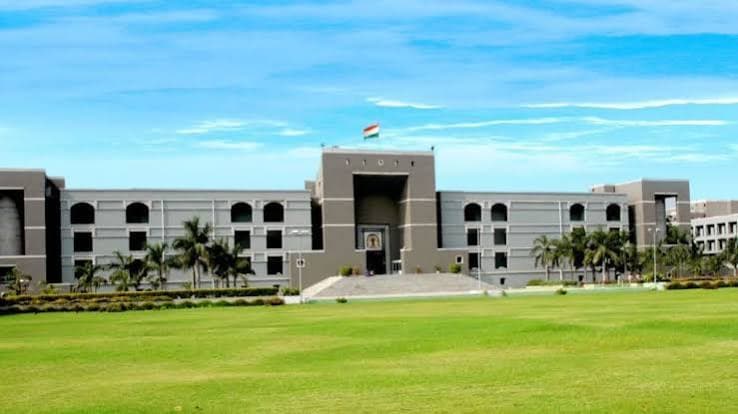
The Gujarat High Court has ruled in favour of the Gujarat Cooperative Milk Marketing Federation (GCMMF), which markets Amul products, quashing a Goods and Services Tax (GST) demand of Rs 43.43 crore imposed over expenses incurred by its head office for services provided to branches and depots.
A bench of Justices A S Supehia and Vaibhavi D Nanavati set aside the January 1, 2025, order issued by the Additional Commissioner of Central GST, Ahmedabad South, which had confirmed an Integrated GST demand of Rs 43,43,12,441, along with interest and penalties.
The dispute concerned common corporate expenses incurred at Amul’s head office in Anand between July 2017 and March 2019. These included advertising, legal services, information technology systems and other administrative costs. Amul had not allocated these expenses to its branches through a mechanism known as “cross-charging”, under which one unit raises an invoice on another for shared services.
The GST department argued that separately registered branches were distinct entities under the law and that the services provided by the head office were taxable. It alleged that the failure to cross-charge the expenses resulted in unpaid tax.
The High Court relied on clarifications issued by the Central Board of Indirect Taxes and Customs (CBIC) concerning the valuation of services between separately registered units of the same organisation.
Under the applicable clarification and Rule 28 of the Central Goods and Services Tax Rules, 2017, the value of certain internally supplied services may be treated as nil where the prescribed conditions are satisfied, including the absence of an invoice and the recipient's eligibility for full input tax credit.
The court noted that the department did not dispute that Amul’s head office had not issued tax invoices to its branches for the services in question. It held that the authorities could not calculate the taxable value merely by distributing common expenses among branches according to their turnover.
The court also questioned the invocation of Section 74 of the CGST Act, which permits extended tax demands in cases involving fraud, wilful misstatement or suppression of facts with the intent to evade tax.
It observed that the expenses were recorded in Amul’s books, ledgers and balance sheets, and that the department had not established deliberate tax evasion. The court consequently quashed the demand, along with the associated interest and penalty.
The ruling highlights the importance of applying prescribed GST valuation rules and establishing evidence of intentional tax evasion before invoking stringent demand provisions.
Germany’s Student of the Year 2027: Nominations open for €5,000 award
UP Scholarship 2026-27: Renewal Deadline October 15, Fresh Applications Open Till October 31; Check Eligibility
MIT Bengaluru Launches Quantum Hub to Advance Quantum Computing Research in India
Italy’s education minister responds to student housing protests, cites 73,223 additional beds
upGrad and MICA Digital Marketing Programme Reaches 100 Cohorts, Trains Over 21,000 Marketers
ICFAI Hyderabad, Sheffield Hallam University sign MoU to strengthen research and academic collaboration
Hindu College protest puts governance, financial transparency and Delhi University's oversight under scrutiny
Ambedkar University Delhi protest: Attendance rules, campus restrictions and suspensions deepen standoff
NEET-UG 2026 paper leak: CBI files supplementary chargesheet against 14th accused
UK visa crackdown drives student withdrawals, putting universities at financial risk
Germany’s Student of the Year 2027: Nominations open for €5,000 award
UP Scholarship 2026-27: Renewal Deadline October 15, Fresh Applications Open Till October 31; Check Eligibility
MIT Bengaluru Launches Quantum Hub to Advance Quantum Computing Research in India
Italy’s education minister responds to student housing protests, cites 73,223 additional beds
upGrad and MICA Digital Marketing Programme Reaches 100 Cohorts, Trains Over 21,000 Marketers
ICFAI Hyderabad, Sheffield Hallam University sign MoU to strengthen research and academic collaboration
Hindu College protest puts governance, financial transparency and Delhi University's oversight under scrutiny
Ambedkar University Delhi protest: Attendance rules, campus restrictions and suspensions deepen standoff
NEET-UG 2026 paper leak: CBI files supplementary chargesheet against 14th accused
UK visa crackdown drives student withdrawals, putting universities at financial risk
Copyright© educationpost.in 2026 All Rights Reserved.